The rooms are ready. The calendar is booked. Guests are expected, and everything is going according to plan, until it isn’t.
For inn and bed-and-breakfast owners, every reservation represents income the business is counting on. But the biggest loss may come from a disruption you never accounted for.
When the Forecast Changes, Bookings Can Disappear
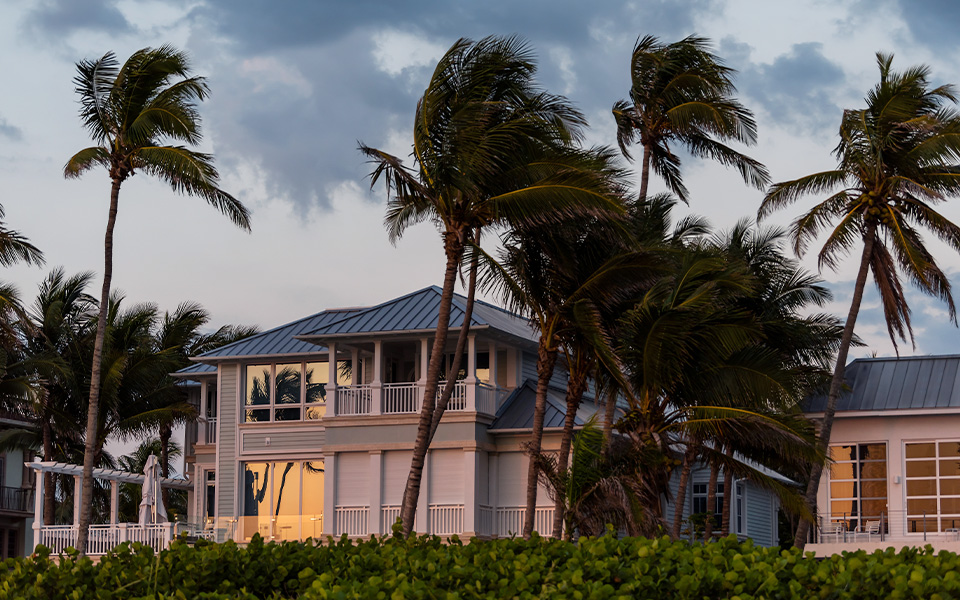
Weather does not have to damage your inn or bed-and-breakfast to disrupt business. When conditions make travel difficult, unsafe, or uncertain, guests may cancel, shorten their stays, or change their plans altogether.
Those cancellations can leave rooms empty with little time to fill them again. Even if your property remains open and fully operational, the opportunity to earn that revenue may disappear with the reservation.
To help retain revenue, act before guests cancel. Reach out when weather may affect upcoming stays, clearly explain available options, and make it easy to move a reservation to another date when appropriate. A proactive response may preserve the booking instead of losing it altogether.
Short Booking Windows Make Income Protection Critical
Most inns and bed and breakfasts don’t earn evenly across the calendar. Revenue arrives in bursts: fall foliage weekends, holidays, ski season, summer getaways, and wedding season. Those few windows carry you through the slow months.
That dependence raises the stakes of every disruption. You can’t resell a canceled October weekend in February at October rates. And when guests book closer to their arrival dates, you have little time to refill rooms once plans fall apart. For a small property, one lost peak weekend can drain the cushion meant to get you through the quiet stretch.
Make Business Income Protection Work Harder
That’s why business income protection deserves more than a quick glance at renewal. When a covered loss forces you to close, the right coverage can replace the net income you would have earned, pay continuing expenses such as payroll, loan payments, and taxes, and cover extra costs that help you reopen faster.
But coverage only protects you if it fits the way your business earns. Ask yourself:
- Does my limit reflect peak season? A limit based on yearly averages can leave you short if a loss hits during your busiest months.
- Can I prove what I lost? Claims rely on your financial records, so keep booking data, profit and loss statements, and tax returns current and easy to find.
- How long is my waiting period? Many policies don’t start paying until a set amount of time passes, which can matter when most of your income comes on weekends.
- How long will recovery take? Reservations rarely bounce back the day you reopen. An extended period of indemnity can keep coverage in place while bookings rebuild.
Keep Empty Rooms From Draining Your Revenue
Connect with CBIZ to review your business income coverage and build a plan that keeps revenue flowing, even when guests can’t make it to your door.
Frequently Asked Questions
Not automatically. If an outage starts at an off-site utility, standard business income coverage may not respond. Utility services time-element coverage may help replace lost income when a covered event damages specified utility equipment. Ask whether your policy includes this protection and whether it excludes overhead power lines.
Not under a National Flood Insurance Program policy. That coverage pays for eligible flood damage to the building and insured contents, not lost rental income or business interruption. Ask your insurance adviser whether private flood coverage can address the income exposure, and confirm the terms before assuming your policy covers a flood-related closure.
It can reimburse a guest’s prepaid, nonrefundable lodging costs when the cancellation meets the policy’s covered reasons. A worrying forecast alone usually does not qualify. Travel insurance protects the guest, not your business’s revenue directly, so it does not replace your own coverage or determine your refund obligations.
This blog may contain scenarios that are provided as examples only. Coverage is subject to the terms, conditions and exclusions of the policy issued. The information provided is general in nature and may be affected by changes in law or the interpretation of such laws. The reader is advised to contact a professional prior to taking any action based upon this information.